Abel Boreto, Investment Director at Novastar Ventures, writes:
Global venture funding rebounded sharply in Q1 2026, driven overwhelmingly by AI. Around $300B was invested globally during the quarter, with almost 80% of capital flowing into AI-related companies — particularly foundational model players like OpenAI, Anthropic and xAI. Capital is increasingly concentrating in fewer, larger companies, while early-stage deal activity continues to slow.
But Africa looks very different.
While funding into African startups increased year-on-year in Q1, much of that growth came from debt rather than equity. At the same time, deal counts (particularly at the early stage) continued to decline.
A few themes stood out to us over the quarter:
Debt is becoming a core part of the African VC landscape
One of the clearest shifts we’re seeing is the growing role of non-dilutive capital in African startup financing.
Debt funding surged across the continent in Q1 and now accounts for a meaningful share of overall startup capital raised. We’re also seeing more sophisticated financing structures emerge, particularly across fintech and climate sectors, including securitisation, mezzanine financing and revenue-based models.
In many ways, this reflects a maturing ecosystem. As businesses scale and revenue visibility improves, founders are looking for more efficient forms of capital beyond pure equity.
We expect this trend to continue.
Climate and e-mobility are reaching real scale
Climate funding continued to build momentum in Q1, particularly across e-mobility and agritech.
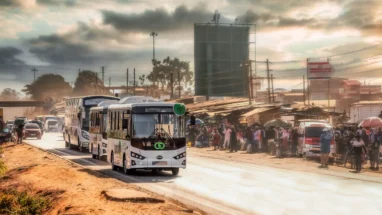
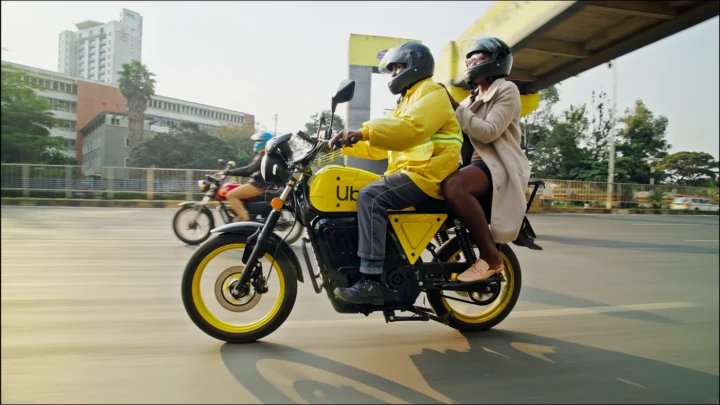
What’s notable now is not simply investor interest, but growing commercial viability. Higher fuel prices, improving infrastructure and supportive regulation are helping accelerate adoption across several African markets.
This is especially visible in electric mobility, where companies are increasingly demonstrating scalable economics alongside strong consumer demand.
For us, this continues to reinforce the long-term opportunity across climate and resource-efficiency sectors.
More capital is flowing to fewer companies
Another trend becoming increasingly obvious is capital concentration.
Across both global and African markets, larger rounds are flowing to a smaller group of more mature companies, while early-stage deal activity continues to soften.
This dynamic is also pushing some of Africa’s larger venture firms to move earlier in the market as they look to build stronger proprietary pipelines for future growth-stage investments.
Africa risks missing the global AI funding wave
While AI dominates global venture markets, Africa remains largely absent from the infrastructure and foundational model layer attracting the bulk of investment.
That said, we believe there is still significant opportunity for locally embedded AI applications across sectors like agriculture, logistics, healthcare, financial services and energy — particularly where businesses combine deep operational understanding with strong distribution.
The question is unlikely to be whether AI reaches Africa (because it already has). The actual question is where enduring value will be created locally.
Continued LP confidence in Africa
Despite a difficult fundraising environment, Q1 also saw several Africa-focused funds reach meaningful milestones (including vehicles focused on agribusiness, climate, aquaculture and broader venture investing).
We feel this is an encouraging signal.
While the market remains challenging, there continues to be strong institutional conviction in Africa’s long-term opportunity — particularly behind experienced managers and sectors solving large structural challenges across the continent.
At Novastar, we continue to see exceptional entrepreneurs building resilient, transformative businesses across mobility, energy, food systems and financial services (often under much tougher operating conditions than their global peers).
That resilience continues to be one of the ecosystem’s greatest strengths.